
Introduction
Within the contemporary financial landscape, people struggling with bad credit score often find themselves in dire circumstances, leading them to contemplate alternative lending options similar to payday loans. In the event you loved this informative article and you would like to receive more info regarding Vetplusav company summary please visit our web site. This case examine examines a selected individual, whom we are going to refer to as Sarah, who sought payday loans with bad credit approval. The exploration of Sarah's experiences highlights the realities, risks, and potential penalties related to these loans.
Background
Sarah, a 32-12 months-previous single mom, just lately confronted a series of unexpected monetary setbacks, including a layoff from her job. With restricted savings and mounting bills, Sarah found herself in a precarious financial scenario. Her credit score score had plummeted on account of previous missed funds, and she was at a loss for methods to cowl her residing bills, main her to discover payday loans as a potential answer.
Understanding Payday Loans
Payday loans are short-term, high-curiosity loans designed to bridge the gap between paychecks. They're marketed to individuals with poor credit histories as a straightforward means of acquiring money rapidly. Approval for these loans typically doesn't take credit score scores into consideration, making them interesting to borrowers like Sarah, who may not qualify for conventional loans. However, the ease of access comes with significant dangers, particularly the potential for exacerbating financial distress.
The appliance Process
After researching payday loan choices online, Sarah determined to apply for a loan by a local payday lender. The method was easy and quick. Sarah stuffed out a web-based application that required minimal documentation, primarily her identification and proof of revenue. Within hours, she obtained a notification that her loan had been accredited for $500, with a repayment expectation due in two weeks, along with a hefty interest charge.
Dangers and Challenges
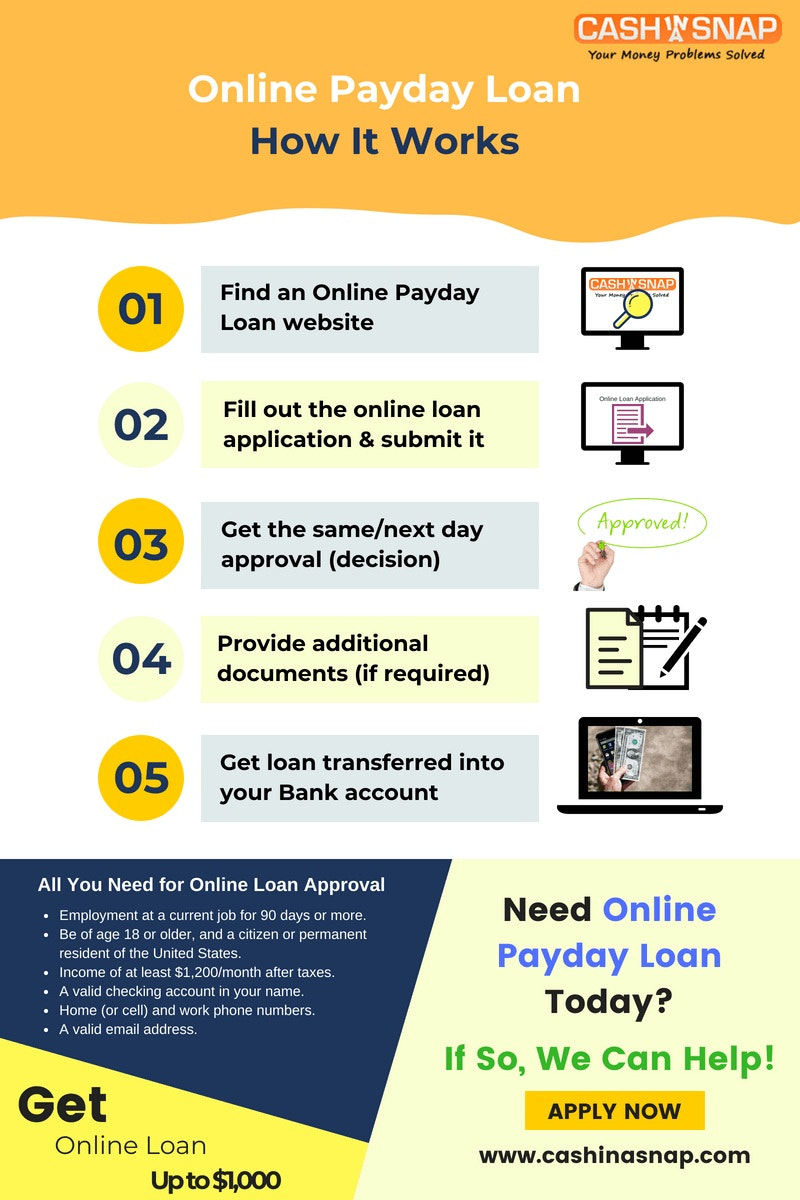
While the quick entry to cash offered immediate relief, it did not come with out pitfalls. The annual percentage charge (APR) on Sarah’s payday loan was an astonishing 400%, considerably larger than different borrowing choices. Together with her repayment due date quick approaching and her monetary situation unstable, Sarah started to acknowledge the unsustainable nature of payday loans. The looming repayment deadline triggered anxiety, and she discovered herself considering a second payday loan to cowl the preliminary loan payment.
Cycle of Debt
Because the repayment date of her first payday loan approached, Sarah struggled to assemble the funds. When the due date arrived, she was unable to pay back the $500 plus interest, as her revenue was inadequate to cowl each her loan cost and essential dwelling bills. Faced with the impossible choice, she took out a second payday loan to repay the first. Unfortunately, this led to a cycle of debt, the place each payday loan only served to create the burden of extra repayments, exacerbating her monetary instability.
Penalties
Sarah’s experience will not be unusual amongst borrowers looking for payday loans, especially these with bad credit score. The implications of her actions became apparent quickly. With every loan taken, the excessive-interest charges piled up, leading to a total repayment obligation that far exceeded the original amount borrowed. Furthermore, her situation deteriorated her credit worthiness much more, because the growing debt led to missed funds on her other accounts as she struggled to manage her finances.
Seeking Alternatives
Realizing that payday loans had been plunging her deeper into debt, Sarah sought various solutions. She consulted a monetary advisor who offered her with a number of choices to regain control of her monetary state of affairs. Among the options were credit score counseling services, negotiating payment plans with creditors, and exploring group assistance programs designed to assist individuals dealing with monetary crises.
Lessons Realized
This case examine highlights vital lessons relating to the dangers associated with bad credit payday loans. While they may seem like a fast repair to a urgent financial drawback, the lengthy-term repercussions often outweigh the advantages. The ease of approval can lead borrowers into a spiral of debt that turns into nearly not possible to flee. The case of Sarah serves as a cautionary tale, urging potential borrowers to think about all available options and perceive the risks concerned in payday lending earlier than proceeding.
Conclusion
In conclusion, Sarah’s expertise with bad credit payday loans illustrates the intricate challenges faced by people in monetary distress. Though payday loans may offer short-term relief, they're fraught with dangers that may result in deeper financial problems. Potential borrowers must conduct thorough analysis and search better alternatives to safe their monetary future. In a society where financial literacy is important, it is crucial to educate people in regards to the pitfalls of payday loans and promote accountable borrowing practices.